
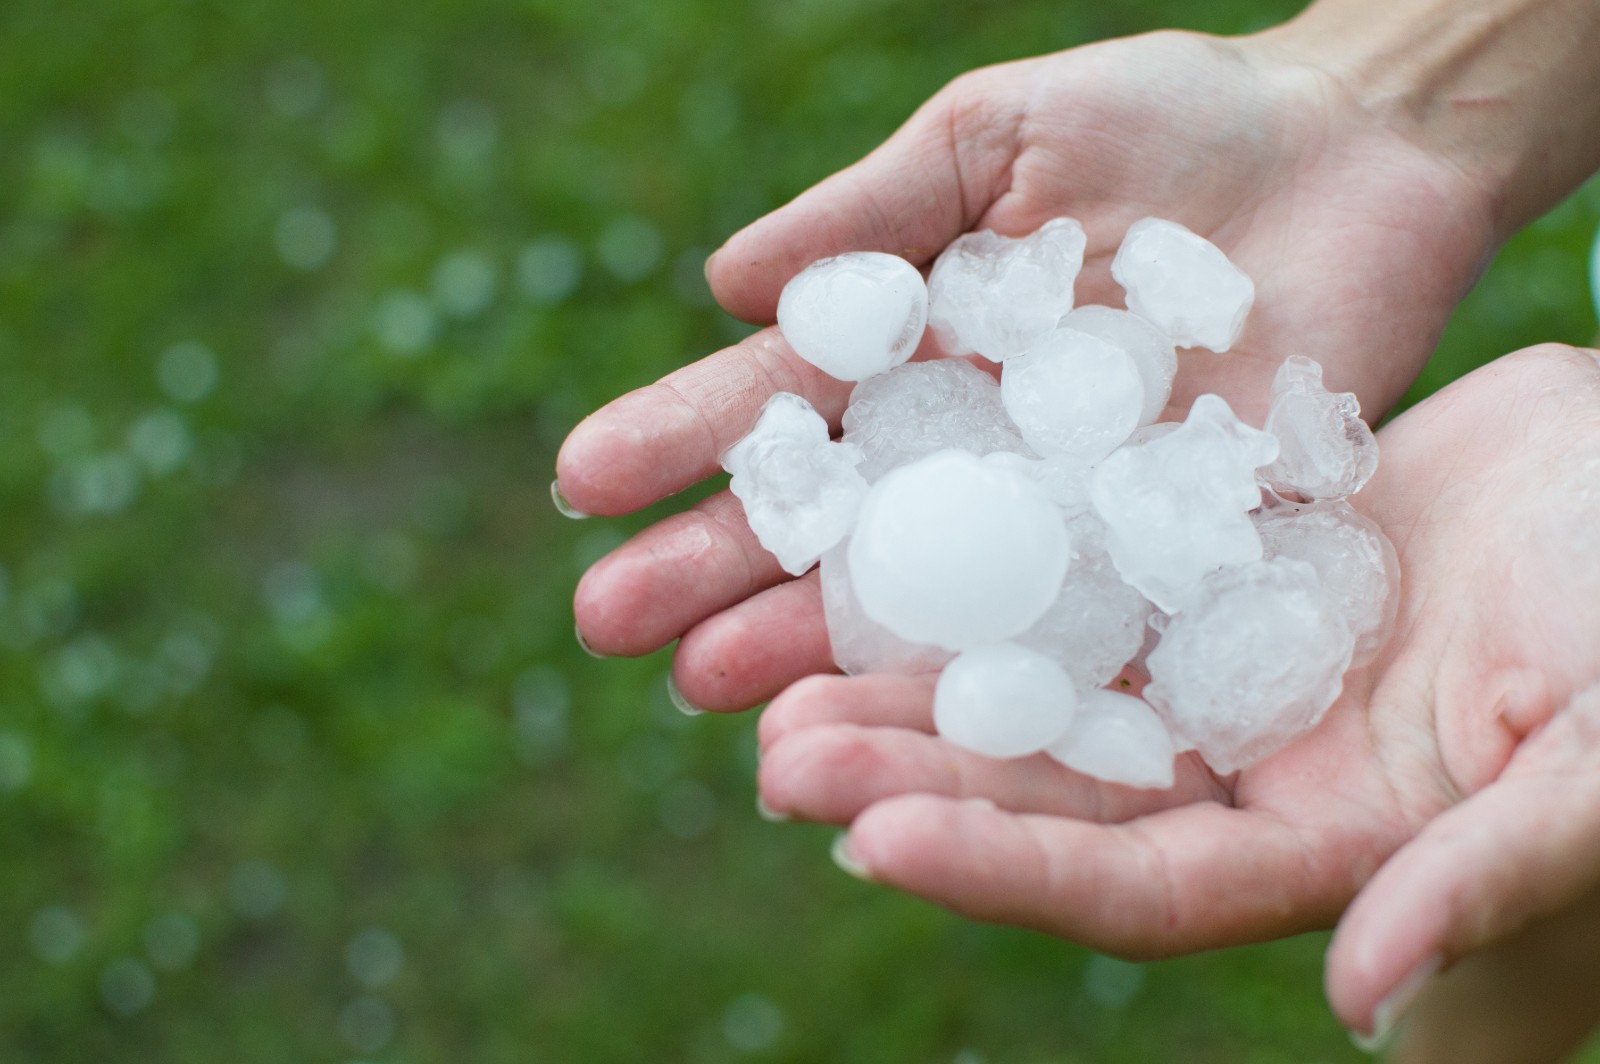
Mountain views are a perk of calling Colorado Springs home. Dents in your hood after a hailstorm? Not so much. When a storm leaves its mark on your car or roof, you want to know what your insurance will actually pay.
Homeowners insurance typically covers hail damage to your home. For your car, hail damage generally falls under comprehensive auto coverage, if you carry it. Your deductible, exclusions and claim settlement terms determine how much you may receive.
At 719 Insurance, we help Colorado Springs residents make sense of those details and compare home and auto policies. Here’s what to know before the next storm rolls across the Front Range.
Does Car Insurance Cover Hail Damage?
Comprehensive coverage generally helps pay for damage caused by hail, including dents and broken glass. You may also see it described as “other than collision” coverage.
Liability coverage alone does not pay for hail damage to your own vehicle. Collision coverage addresses crashes and similar impacts, rather than damage from hailstones.
That means having car insurance doesn’t automatically mean you have hail coverage. Check your policy’s declarations page for comprehensive coverage and its deductible. The NAIC’s guide to auto insurance coverage explains how these protections differ.
For a simple example, suppose your insurer approves $3,000 in covered hail repairs and your comprehensive deductible is $500. Assuming no other adjustments apply, insurance would pay $2,500 and you would be responsible for the deductible.
Also ask about rental reimbursement. Coverage for repairing your car doesn’t automatically mean the cost of a rental is included while it’s in the shop.
Does Homeowners Insurance Cover Hail Damage?
Homeowners insurance commonly covers direct hail damage to your house, which may include the roof, siding and windows. However, the policy’s exclusions and settlement terms still apply.
A covered hail claim also doesn’t automatically mean your insurer will pay for an entirely new roof. The extent of the damage and your policy determine whether the covered work involves repairs or replacement.
One of the most useful questions to ask is: How would my policy pay a roof claim?
With replacement cost coverage, payment is generally based on the cost of repairing or replacing covered damage with comparable materials, subject to policy conditions. Actual cash value coverage accounts for depreciation, which can reduce the payment for an older roof.
Review roof coverage at renewal, too. Don’t assume the terms stay the same from one year to the next.
How Does a Wind and Hail Deductible Work?
Your homeowners policy may have a wind and hail deductible that differs from the deductible for other covered losses. It may be a fixed dollar amount or a percentage of your home’s insured dwelling value.
For example, if a policy has a 2 percent wind and hail deductible based on $400,000 in dwelling coverage, the deductible is $8,000.
That’s 2 percent of the insured dwelling amount — not 2 percent of the repair bill.
This is an illustration, not a standard deductible for every Colorado policy. Check the amount and calculation in your own documents before comparing quotes. A percentage that looks small can represent a significant out-of-pocket expense.
If the same storm damages your home and car, expect the losses to be handled under their respective coverages. Ask how each deductible applies and whether your insurer offers any provision that changes what you owe when both are damaged in one event.
What Should You Do After a Hailstorm?
Start with safety, then focus on documenting the damage and understanding the claim process.
- Wait until conditions are safe. Inspect from the ground rather than climbing onto a potentially damaged roof.
- Take photos and notes. Document visible damage to your home and vehicle, along with the storm’s date and approximate time.
- Contact your insurer promptly. Ask about reporting deadlines, inspections and the documentation needed for each claim.
- Prevent further damage when it’s safe. Arrange necessary temporary protection for openings or broken windows, and keep receipts.
- Coordinate permanent repairs. Confirm what your insurer needs to inspect before work begins, and retain written estimates and repair records.
Prompt reporting and good documentation help your insurer evaluate what happened. Temporary repairs can also help prevent the original damage from becoming a larger problem.
Why Review Hail Coverage in Colorado Springs?
Hail is part of the local severe-weather picture. The National Weather Service’s regional severe-weather data includes hail reports for the area served by its Pueblo office, including El Paso County.
A useful coverage review starts with a few specific questions:
- Does each vehicle have comprehensive coverage?
- What deductible applies to each vehicle?
- How is the roof insured?
- Is there a separate wind and hail deductible?
- Are there roof-specific exclusions or limitations?
- What would we need to pay out of pocket after a covered storm?
You don’t need to become an insurance expert. You do need clear answers about the policy you’re paying for.
Find Home and Auto Coverage You Understand
Your home and car may weather the same storm, but their insurance works differently.
719 Insurance helps Colorado Springs residents compare coverage from multiple carriers and understand the details that affect a claim. We’ll walk through your options, explain the deductibles and help you find policies that fit your needs and budget.
Explore our home and auto insurance options and connect with our team to find the right coverage before the next hailstorm.